A family can be well protected without having flawless finances. What it needs is a workable plan for the moments when a paycheck stops, a large bill lands, a household member becomes disabled, or a parent passes away without warning. Family protection planning pulls those risks into one view and gives your household a straightforward way to get ready for them.
For households in the U.S., the plan may draw on life insurance, health and disability coverage, emergency savings, debt control, beneficiary designations, estate paperwork, and a routine check-in. Life insurance is a valuable piece, though it is only one piece.
Key Takeaways
- Family protection planning goes beyond buying a life insurance policy; it means preparing for several financial risks that could hit your household.
- Begin with the people who rely on your income, unpaid caregiving, or other financial support.
- Size life insurance by weighing income replacement, debts, future goals, final expenses, and available resources instead of leaning on one rule of thumb.
- Hold an emergency fund apart from insurance, since insurance and cash savings solve different problems.
- Check employer-provided coverage, beneficiary designations, wills, powers of attorney, and key account information.
- Revisit your plan after major events like marriage, divorce, a birth or adoption, a home purchase, a big career move, or a notable change in income.
- U.S. government benefits and tax rules add useful context, but they are no substitute for a plan built around your household.
What Is Family Protection Planning?
Family protection planning means spotting the financial risks a household faces and then lining up money, insurance, paperwork, and clear instructions to soften the blow if those risks happen.
Nobody can forecast every emergency, and the aim is not to try. The aim is for the family to know how it would respond if a serious financial shock hit. In practical terms, family protection planning converts uncertainty into decisions you can revisit and adjust.
In one home, the largest exposure may be losing the main income, and family protection planning places that risk next to the household’s other risks rather than looking at it alone. In another, it may be a disability, steep medical bills, a mortgage, the cost of raising children, or the death of a spouse who provides unpaid care.
For that reason, a protection plan works best when it begins with what the family actually owes and provides, not with a specific insurance product.
According to the National Association of Insurance Commissioners (NAIC), life insurance can shield loved ones from financial hardship once the insured person has died. The NAIC adds that how much coverage makes sense varies with things like household income, debt, schooling costs, funeral and other final expenses, inflation, and who depends on the insured.
It helps to picture family protection planning as a financial safety net built from several layers:
1. Cash reserves for short-term shocks.
2. Insurance for risks that could create large losses.
3. Debt and cash-flow planning to keep obligations manageable.
4. Legal and beneficiary documents that help direct assets and decision-making.
5. Regular reviews so the plan changes as the family changes.
Why Does Family Protection Planning Matter?
Even a household with strong earnings can be financially fragile. Good family protection planning looks at what happens when circumstances shift, not merely at today’s paycheck.
Picture a family with two children and a mortgage. When one parent dies, the other may lose income while childcare, housing, schooling, and everyday costs carry on. If the surviving parent cannot work, the problem looks different but can be just as serious.
Insurance moves certain risks onto an insurer, and savings supply ready cash for costs a policy may not pay. Legal documents, meanwhile, can let someone step in on financial decisions when a person is unable to handle their own affairs.
The Consumer Financial Protection Bureau (CFPB) frames an emergency fund as cash reserved for surprises like repairs, medical bills, or a drop in income. With savings on hand, the agency says, households can absorb financial shocks without leaning so heavily on credit or loans.
The difference is important. Insurance responds to specific risks according to the policy’s terms, whereas an emergency fund can be tapped right away for whatever household need arises. A strong plan uses both, so that savings and insurance together act as a financial safety net for different kinds of risk.
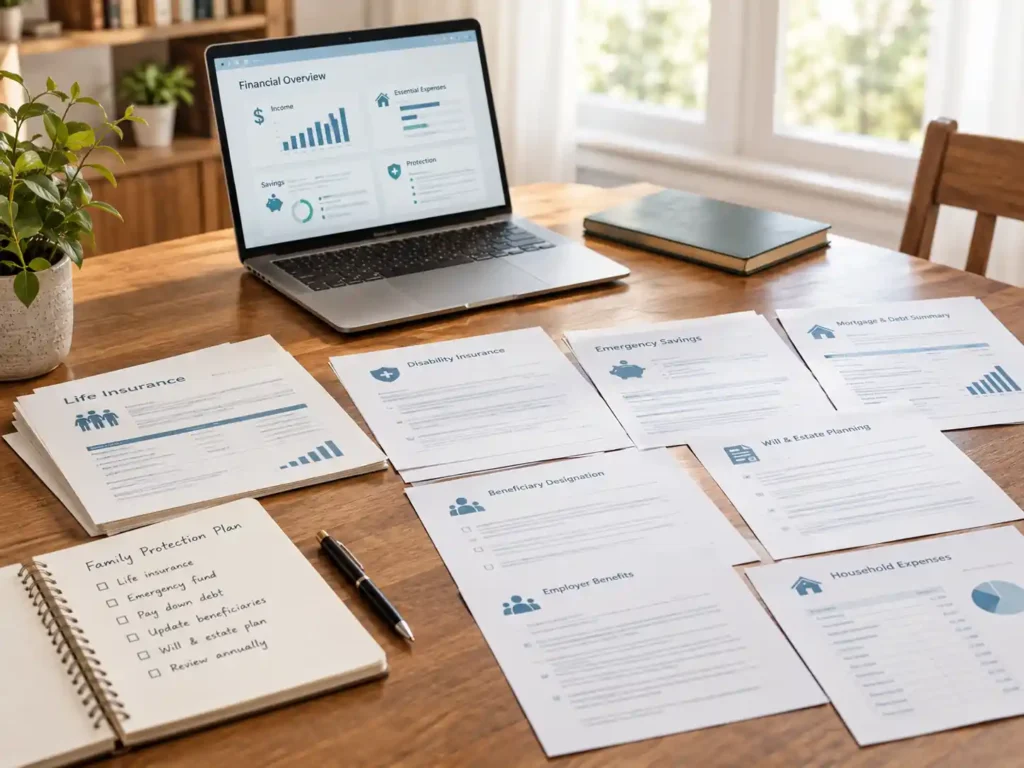
The 7 Core Steps of Family Protection Planning
1. Map Your Family’s Financial Dependence
Begin by writing down everyone who relies on the household, whether for money or for unpaid support. It is among the most useful first moves in family protection planning because it shows who would feel the impact if income or caregiving disappeared.
The list might include a spouse or partner, children, an aging parent, a relative with special needs, or anyone else counting on your income or care.
Next, note the services each adult contributes. Income is easy to see, yet unpaid work carries real financial value too. Childcare, driving, running the home, and caregiving could turn into paid expenses if the person doing them were no longer there.
Then put together a quick household snapshot:
- Essential monthly expenses
- Housing payment
- Childcare and education costs
- Health-related costs
- Minimum debt payments
- Yearly or irregular expenses
- Retirement contributions
- Savings and investments on hand
- Existing insurance
- Employer benefits
- Any other expected income or benefits
This exercise gives family financial protection a starting point, since it reveals which costs would keep going after a major life change. Family financial protection also covers the income and unpaid services a household would have to replace.
2. Estimate the Life Insurance Gap
When anyone in the household has financial dependents, life insurance may deserve a central place in the plan.
The question is not simply, “How much insurance should I buy?” In family protection planning, a more helpful question is how much money the household would really need to cover the shortfall. That is a core family protection planning question, because coverage should tie back to a genuine need. Try asking instead, “What financial gap would my family face if my income and support disappeared?”
A practical needs-based estimate can weigh the items below. Family protection planning should also factor in how long the household would need support, not just the size of today’s income.
- Income that may need to be replaced
- Outstanding mortgage and other debts
- Childcare costs
- Education goals
- Final expenses
- Ongoing household expenses
- Financial support for dependent relatives
- Available savings and investments
- Existing individual and employer-provided life insurance
- Potential survivor benefits or other resources
- Inflation and the time period for which support may be needed
The NAIC stresses that life insurance needs differ from person to person, and it urges consumers to weigh household income, dependents, education, debts, final expenses, and future inflation when settling on an amount.
You may run across simple rules that point to a multiple of annual income. Those shortcuts can open the conversation, but they ignore each household’s particular debts, assets, caregiving needs, and goals.
Families often turn to term life insurance when they need significant protection for a set stretch of time, like the years children are dependent or a mortgage is being paid down. Permanent policies, such as whole life and some universal life products, can last longer and may build cash value. Costs, guarantees, risks, and terms vary, so any policy should be measured against the real need.
Avoid canceling a current life insurance policy just because you are looking at a new one. The NAIC advises carefully comparing the old and proposed coverage before you replace anything.
3. Protect the Income Behind the Plan
Family financial planning often leans too hard on death protection and forgets the case where an earner survives but cannot work.
A disability can disrupt household cash flow well before retirement, and its financial effects are not the same as those of a death.
Look at what your employer offers for disability income, life insurance, health insurance, and other benefits. Then work out what would happen if you changed jobs or the employer-sponsored coverage came to an end.
The NAIC explains that disability income insurance can replace part of your earlier income if a covered disability keeps you from working. Employer benefits may offer some protection, but coverage details, eligibility, waiting periods, how long benefits last, and exclusions all vary by plan.
Health insurance deserves a look too. In family protection planning, medical costs and access to care merit attention right next to income protection. A serious illness can generate bills even while paychecks keep coming, and losing employer coverage can change how a household gets health insurance.
The objective is not to buy every policy on the market. Family financial protection should follow the size and type of risk rather than a product checklist. The task is to pinpoint the risks that could seriously damage your family’s finances and decide which ones insurance, savings, or other resources can handle.
4. Build a Dedicated Emergency Fund
An emergency fund is among the most straightforward layers of a financial safety net.
It can cover costs like a big car repair, a surprise medical bill, a short gap in income, or an urgent fix at home. A dedicated cash reserve keeps such events from derailing long-term goals.
No single emergency-fund figure suits every household. The right amount turns on how stable your income is, essential expenses, dependents, insurance deductibles, debt, job security, and what other resources you can reach.
A household living on variable self-employment income may need a larger or different cushion than one with two steady salaries. Family protection planning should account for that gap instead of applying one savings target to everyone.
Keep the money easy to reach but set apart enough that it does not slip into everyday spending. That small separation makes family protection planning easier to sustain. The CFPB suggests weighing safety and accessibility when choosing where emergency savings should sit.
Emergency savings should not be mixed up with long-term investments either. Cash meant for a near-term emergency does a different job than money earmarked for retirement decades away.
5. Review Beneficiaries and Essential Documents
A life insurance policy delivers on its purpose only if the right people can find it, file a claim, and understand the instructions that come with it.
Go over the beneficiaries named on your life insurance policies and retirement accounts. Confirm that primary and contingent beneficiaries are up to date and still reflect what you want.
As the NAIC points out, life insurance benefits typically go to the beneficiaries you name, and it is wise to revisit those choices from time to time.
Also draft or refresh the legal documents that fit your situation, such as a will, powers of attorney, and health-care directives.
A financial power of attorney lets someone you trust act for you if you can’t handle money matters yourself. The CFPB says a durable version can support planning for future incapacity, but cautions that you should choose the person holding that authority with great care.
Maintain a secure record of:
- Insurance policy information
- Employer benefit details
- Bank and investment account information
- Mortgage and loan details
- Beneficiary designations
- Estate documents
- Key professional contacts
- Instructions for accessing important records
Sensitive account numbers do not belong in a shared household checklist. What matters is that the right person can locate the correct documents when the time comes.
6. Coordinate Insurance With Debt, Savings, and Long-Term Goals
Protection should not sit apart from the rest of your finances. Strong family protection planning ties insurance choices to savings, debt, retirement goals, and household cash flow.
Imagine a family with a mortgage, student loans, retirement savings, college goals, and a life insurance policy. The coverage amount should be weighed against the resources already in hand and the obligations that would remain.
The same logic holds for employer life insurance. Family financial planning should consider what becomes of that benefit if your job changes. Employer coverage can be worthwhile, yet it may depend on staying employed or carry limits specific to the plan. Find out what happens to it if you leave.
This is where life insurance planning proves more valuable than just shopping for a policy. Good life insurance planning links the policy to the household’s broader financial plan, so protection works in step with everything else the household has set up.
One sensible order of operations:
First, get clear on essential expenses and debts.
Next, take stock of the resources and benefits you already have.
Then estimate the shortfall a death or disability would leave.
After that, decide which risks insurance should cover and which can be met with savings or other assets.
Finally, confirm that premiums and other costs remain affordable over the long run.
The lowest-priced policy is not automatically the best fit if it expires too soon or falls short on protection. On the other hand, an elaborate policy can add needless cost when the household mainly needs plain income protection.
7. Review the Plan After Major Life Changes
Family protection planning works better as an ongoing process than as a one-time purchase. A living plan stays accurate more easily, since coverage, beneficiaries, income, and family duties all shift over time.
Review the plan when you: A recurring family protection planning review can go on the calendar so it does not rely on memory during a hectic life transition.
- Get married or divorced
- Have or adopt a child
- Buy or refinance a home
- Take on significant new debt
- Change careers or employers
- Become self-employed
- Experience a major change in income
- Start supporting a parent or another dependent
- Retire or approach retirement
- Receive a large inheritance or other major asset
- Change your estate-planning documents
Even when nothing major has happened, a periodic review can catch outdated beneficiaries, expired documents, coverage that has fallen short, or shifts in household spending.
An annual review can be brief. Compare today’s income, debts, dependents, savings, employer benefits, and insurance with the figures you used when you built the plan.
Family Protection Planning and Social Security Survivor Benefits
Some U.S. families can receive Social Security survivor benefits when a worker who paid into Social Security dies.
The Social Security Administration (SSA) lists certain spouses, divorced spouses, children, and dependent parents among those who may qualify. Whether someone is eligible, and for how much, hinges on their relationship to the worker, their age, their circumstances, and the worker’s earnings record.
These benefits can matter a great deal to a household, yet they are best viewed as one possible resource, not a full substitute for private protection.
The SSA also points out that survivor benefits come with specific rules, including some tied to age and earnings. Families should consult current SSA guidance for their own situation instead of trusting a rough estimate.
Are Life Insurance Proceeds Taxable?
Under IRS guidance, death proceeds a beneficiary receives from life insurance are generally left out of gross income for federal income tax purposes. Interest earned on those proceeds, however, can be taxable, and unusual circumstances can alter the treatment.
So a family should not assume every payment tied to a life insurance policy is taxed the same way.
Estate-tax questions are a separate matter from ordinary income tax. Bigger estates and certain ownership setups may call for professional tax or estate-planning advice.
Since tax rules and personal circumstances change, rely on current IRS guidance and qualified professional advice for decisions about a particular policy, estate, or tax return.
Common Family Protection Planning Mistakes
Waiting until a major life event occurs
Insurance and financial planning are easier to sort out before a crisis hits. Waiting can leave a household exposed just when protection matters most.
Relying on employer coverage alone
Employer benefits can be a meaningful layer of protection, but they may change when your job does. Know what you have, what it costs, and what happens if you leave.
Using one income multiple as the entire calculation
Income matters, but it is not the only factor. Debts, childcare, education, savings, current coverage, and how long protection must last all count too.
Forgetting the stay-at-home parent or caregiver
A household can be badly disrupted even when the person who dies never drew a paycheck. Paying for childcare, transportation, housework, and caregiving adds up quickly.
Leaving beneficiary information outdated
Marriage, divorce, remarriage, births, deaths, and similar events can leave an old beneficiary designation out of line with what you want now.
Treating insurance as an investment substitute
Insurance and investments serve different purposes. A protection decision should start with the risk you want to transfer, not with the chance of building cash value. Life insurance planning is clearer when protection needs are kept apart from investment goals.
Ignoring the policy details
Premiums, exclusions, renewability, conversion provisions, guarantees, riders, and benefit conditions all differ from policy to policy. Read the documents and ask questions before you commit.
How to Start Family Protection Planning This Week
You don’t have to solve everything at once. Family protection planning can start with a one-page inventory and a short list of the risks your household would find hardest to absorb.
Begin with a one-page household inventory, which gives family financial planning a concrete place to start.
Note the people who depend on your income or care. Then list essential monthly expenses, debts, savings, current insurance, employer benefits, and big future obligations.
Then pinpoint the single biggest financial risk.
For many families, that is the early death of an earner. For others, disability, health costs, or thin liquid savings may deserve more attention.
Next, cover the basics.
Verify your life insurance beneficiaries. Locate your policy documents. Look over employer benefits. See whether you have an emergency fund. Make sure the people who might need to help you know where key documents are kept.
Finally, book a formal review if the numbers are complicated or your situation has changed a lot. Depending on the question, a licensed insurance professional, financial planner, tax professional, or estate-planning attorney may be the right person to consult.
Frequently Asked Questions
1. What does family protection planning include?
Family protection planning can cover life insurance, disability and health coverage, emergency savings, debt management, beneficiary designations, estate documents, and a routine for reviewing the plan. The right mix depends on who relies on the household financially and which risks would do the most damage.
2. How much life insurance does a family need?
No single amount fits every family. Begin with the income and services that would need replacing, then factor in debts, housing, childcare, education, final expenses, existing assets, current insurance, and how long support may be required. A needs-based calculation tells you more than an income multiple alone.
3. Is life insurance enough for family protection planning?
No. Life insurance mainly deals with the financial fallout of an insured person’s death. A broader protection plan can also handle disability, health costs, emergency expenses, debt, legal decision-making, and access to key financial records.
4. When should you review family protection planning?
Revisit it after big events like marriage, divorce, a birth or adoption, buying a home, taking on major debt, a career or income change, or a shift in dependents. Regular check-ins also keep beneficiaries, coverage, and documents current.
5. What should I do first if I have no family protection plan?
Start by pinning down financial dependents, essential expenses, debts, savings, existing insurance, and employer benefits. Next, find the biggest threats to the household’s ability to cover those expenses. From there you can decide where insurance, savings, legal documents, or other tools fit.
Bottom Line
Family protection planning is not about stacking up a complicated collection of financial products. It is about pairing practical protections with the risks your household truly faces, so there is a realistic response when something threatens to change its financial life.
For many U.S. families, that means pairing suitable life and disability coverage with emergency savings, manageable debt, current beneficiary designations, basic estate documents, and regular reviews. Together these give family protection planning a wider role than life insurance alone.
The most useful plan mirrors your family’s real responsibilities, supports a practical financial safety net, stays affordable, and can be understood by the people who may have to rely on it. In that sense, family protection planning is as much a conversation as a financial exercise. Start with the biggest risks, document what you already have, close the most important gaps, and revisit the plan as your family and finances change.
Complimentary Financial Needs Analysis: 5 Essential Steps
October 7, 2026[…] free financial needs analysis meetings are perfectly fine. A few warning signs, though, deserve your […]