Debt protection and income protection both answer one uncomfortable question: what happens to your bills if your earnings suddenly stop? Most of us insure our phones and vehicles without a second thought, yet the income that pays for everything often goes unprotected.
This guide explains how debt protection and income protection work in plain language, where each one fits into everyday money planning, and what to check before you buy.
Key Takeaways
- Income protection insurance replaces a portion of your earnings when illness or injury stops you from working.
- Debt protection insurance helps with repayments on a specific loan or card when a covered event happens.
- Debt protection and income protection solve different problems, and some households benefit from having both.
- When comparing debt protection and income protection, look at the coverage amount, premium, claim process and exclusions instead of choosing on price alone.
- Your savings, employer benefits and existing policies all affect how much extra coverage you really need.
- A licensed insurance agent or financial advisor can match financial protection to your income, your loans and your family responsibilities.
What Debt Protection and Income Protection Actually Mean
Here is the simplest way to think about it. Income protection looks after you and your monthly earnings. Debt protection looks after one specific loan or card balance.
Income protection insurance, known in the US as disability insurance, pays a regular amount when an illness or injury stops you from working. The money is meant for everyday life, such as rent or mortgage payments, groceries, school costs and utility bills.
Debt protection insurance works differently. It is linked to a particular loan, such as a mortgage, auto loan or personal loan, or to a credit card. If a covered event happens, the plan may pause, reduce or clear your repayments, depending on its terms.
Both types of coverage share the same goal, which is to stop one setback from turning into a long financial struggle. They simply guard different parts of your budget.
How Income Protection Works in Everyday Life
You choose a monthly amount to protect when you buy the policy. Insurers usually limit it to a portion of your earnings, because the idea is to support you, not to leave you better off than when you were working.
Three settings shape how a policy behaves.
- Waiting period: the gap between the day you stop working and the day payments begin (in the US, often called the elimination period). A longer wait often means a lower premium, so it helps to match it with your savings and any paid sick leave or short-term disability benefits from your employer.
- Payout period: how long benefits continue (in the US, often called the benefit period). Some policies pay for a few years, others until a chosen age, often retirement.
- Definition of being unable to work: some policies pay if you cannot do your own job (own-occupation), while others pay only if you cannot do any work at all (any-occupation). This one clause can change the outcome of a claim.
How Debt Protection Works When Repayments Get Hard
Debt protection is usually offered when you take a loan or a credit card, though it can sometimes be added later. You pay a charge, often built into your repayment, and in return the plan may step in if a listed event occurs. Think of it as loan protection for one particular debt.
Listed events commonly include job loss, serious illness, disability or death. What happens next depends on the plan. Some cover repayments for a fixed period, some clear part of the balance, and many set a limit on what they will pay.
Two points are worth remembering. It protects only the loan it is linked to, not your other bills. And in most cases it is optional, so you should never feel pushed into it just to get approved for credit.
In the US, debt protection is sold either as credit insurance, which state insurance departments regulate, or as a debt cancellation or debt suspension agreement offered by the lender. If the coverage is optional, federal Truth in Lending rules (Regulation Z) generally require the lender to tell you so in writing, along with the cost, before you agree to buy it.
Debt Protection and Income Protection: Key Differences
A side-by-side view makes the difference easier to see.
| Debt protection | Income protection | |
| What it protects | Repayments on one named loan or card | Your regular monthly earnings |
| Usual trigger | Listed events such as job loss, illness, disability or death | Illness or injury that stops you from working |
| How help arrives | Repayments are paused, reduced or paid by the plan | A regular income is paid to you |
| How you can use it | Only for the linked debt | For any household cost |
| Worth checking | Which events qualify, benefit limits, cancellation terms | Waiting period, payout period, definition of unable to work |
Put simply, one protects a debt and the other protects your pay. Neither one replaces the other.
Real-Life Situations Where Each Type of Coverage Helps
Here is how debt protection and income protection look in three everyday situations.
A self-employed designer breaks an arm and cannot work for a few months. There is no paid sick leave from an employer to fall back on. Income protection could keep household money coming in while the designer recovers.
A salaried employee with a mortgage and a car loan loses a job unexpectedly. A plan linked to those loans may pause repayments for a period, depending on its terms, which gives some breathing room while looking for new work. Most income protection policies focus on illness and injury rather than job loss, so reading the wording matters here.
A parent who is the main earner falls seriously ill. Medical bills arrive just as earnings slow down. Health insurance can help with treatment costs, income protection can help with groceries and school costs, and debt protection can help keep the loan payment on track.
Where Debt Protection and Income Protection Fit in Your Financial Plan
A sound plan usually has layers. An emergency fund comes first and covers a few months of essentials. Health insurance handles medical bills, and life insurance supports your family if you are no longer around. Then comes the layer that guards your earnings.
That last layer matters for long-term goals. When income stops, retirement contributions (such as 401(k) or IRA deposits) and regular savings often stop with it, or get drawn down to pay monthly bills. Income protection insurance can help you keep those goals on track, because it replaces earnings and leaves your savings for what they were meant for.
Debt protection and income protection can also work as a pair. One keeps the household running, while the other stops a particular loan from falling behind. Whether you need both depends on the size of your loans, the savings you hold and the number of people who depend on you.
None of this replaces good habits. Coverage works best alongside a realistic budget, steady saving and a regular review as life changes. That is what real financial protection looks like in practice.
What to Check Before You Buy Debt Protection and Income Protection
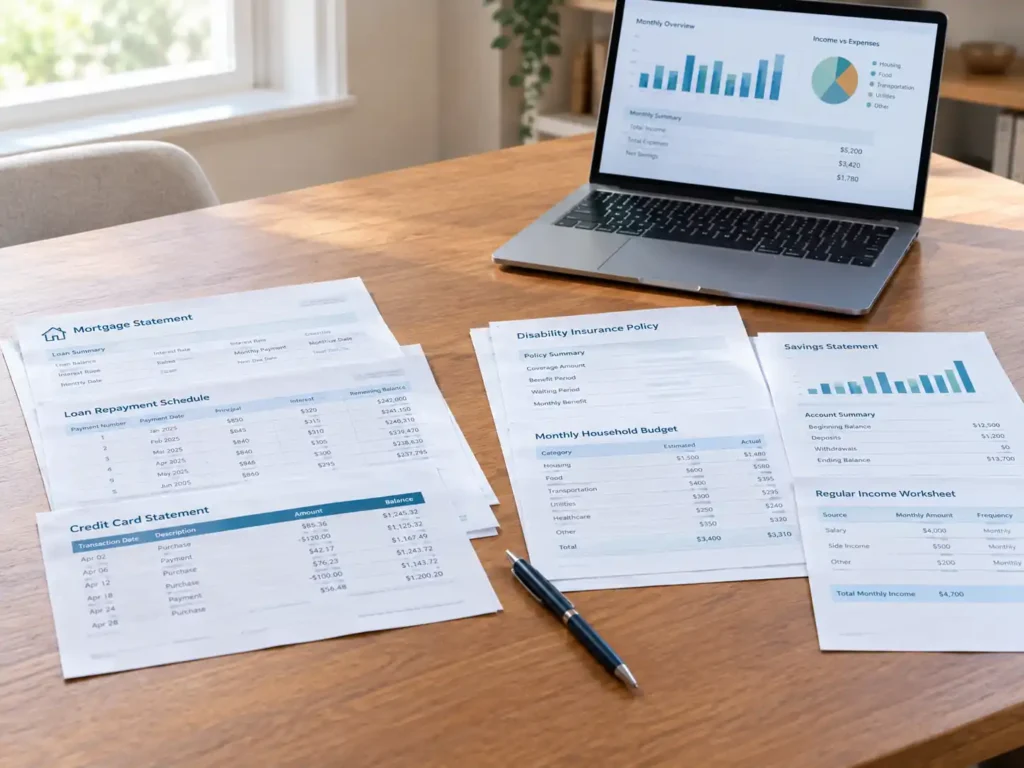
A policy that looks affordable can still disappoint at claim time. Use this checklist for any debt protection and income protection plan you consider.
- Coverage amount: Does it match your essential monthly costs, including loan payments, food, utilities and children’s expenses? For loan protection, does it suit the outstanding loan?
- Premium: Can you comfortably keep paying it for the full term? Also check whether the cost can change over time.
- Claim process: Which documents are needed, how long does assessment usually take, and who do you contact when you need help?
- Exclusions: Look closely at limits on existing health conditions, risky activities, waiting periods before coverage begins, and events the plan does not cover.
- Scope and flexibility: For debt protection, which loans are included and can you cancel if your situation changes? For income protection, do the waiting and payout periods suit your savings and paid sick leave?
- Honest disclosure: Give accurate details when you apply. Wrong information can lead to a rejected claim.
Protection for Self-Employed and Gig Workers
If you freelance, drive for a rideshare or delivery app, or run your own business, you are usually responsible for building your own safety net. In the US, independent contractors generally do not receive employer-provided disability benefits or paid sick leave, and they typically are not covered by workers’ compensation or state unemployment benefits.
- Check your state: A handful of states run their own temporary disability programs, and some let self-employed people opt in. Find out what your state offers.
- Do not rely on Social Security alone: Social Security Disability Insurance is a safety net for severe conditions expected to last at least a year, so it is not a substitute for a private income protection policy.
- Expect income documentation: Insurers typically base the benefit on the net income shown on your tax returns, and uneven earnings are often averaged over a couple of years. Keeping clean records makes it easier to qualify for the amount you want.
- Check debt protection eligibility: Many plans are written with employees in mind, so confirm whether job-loss benefits apply to self-employed borrowers.
Frequently Asked Questions
What is the difference between debt protection and income protection?
Debt protection looks after repayments on a specific loan or card when a covered event happens. Income protection replaces part of your earnings when illness or injury stops you from working, and you can spend that money on anything. In short, one guards a debt and the other guards your pay.
Is debt protection insurance worth it?
It depends on your situation. As a form of loan protection, it can be useful when a loan is large, your savings are thin and your household relies on one income. If you hold healthy emergency savings, or already have other cover that handles loss of income, you may not need it. Compare the total charges, exclusions and benefit limits before you decide.
Is income protection insurance worth the money?
For many people with dependants, loans or limited sick leave, it deserves serious thought, because it protects the earnings behind every other goal. If your employer already offers generous long-term support, or your savings could carry you through a long break, the need is smaller. The policy details matter more than the headline price.
What does income protection not cover?
Exclusions differ from one policy to another. Common ones include job loss, health conditions that were not disclosed or were specifically excluded, claims during the waiting period, and injuries linked to certain risky activities. A normal pregnancy is usually not treated as an illness either. Always read the policy wording before you buy.
Do I need both debt protection and income protection?
Not always. Debt protection and income protection overlap in places, but income protection is broader because the money can go toward any bill, while debt protection is narrower and tied to one loan. If your income cover already looks after your loan instalments, extra debt cover may overlap. A household with large loans and a single earner may want both. A licensed advisor can help you work this out.
Bottom Line
Debt protection and income protection are two practical ways to stop an unexpected setback from undoing years of careful saving. Income protection supports your whole household budget, while debt protection looks after a particular loan.
Start with your savings, your loans and the people who rely on you. Then compare the cover amount, premium, claim process and exclusions of each plan. Before you choose a policy, speak with a licensed advisor who can look at your full picture and guide you toward financial protection that suits your family.
Protection Strategies: 5 Proven Ways to Safeguard Assets
October 7, 2026[…] Trade secrets in the U.S. are protected by the federal Defend Trade Secrets Act and by state laws. The common requirement is that you took reasonable steps to keep the information secret. In practice that means NDAs, need-to-know access, marked confidential documents and a careful offboarding process. Add confidentiality and invention-assignment clauses to employee and contractor agreements too, so that what your people create belongs to the company. […]